Buyer Navigator™
Buyer representation and deal stress testing
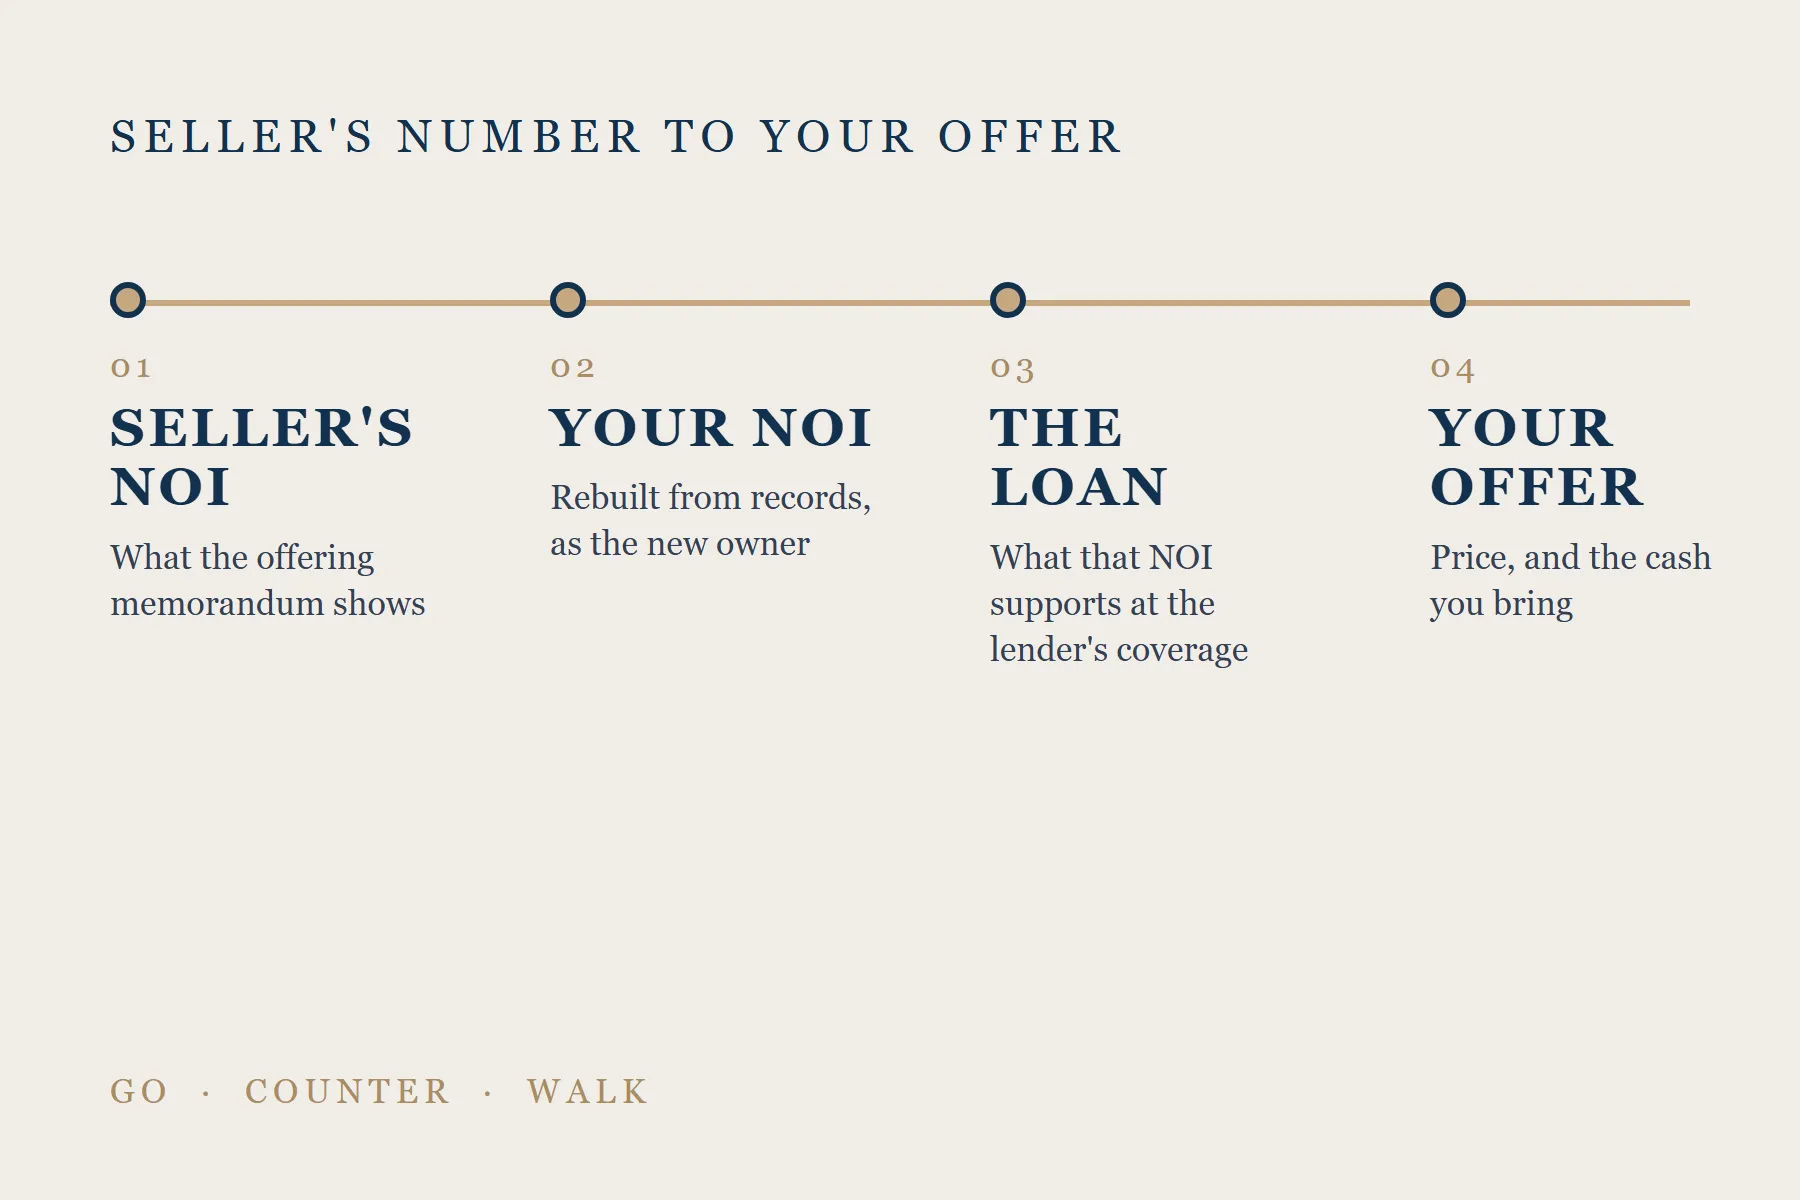
Price follows net operating income. The offering memorandum shows the seller’s version of it.
Buyer Navigator rebuilds that number from the records, the way a new owner will run the building, before you write an offer. Then it carries the deal through due diligence and closing. I represent buyers and sellers of 4 to 50 unit apartment buildings in Washington DC, Virginia, and Maryland, where I am licensed. This is the buyer’s side of the work.
The engagement, start to finish
-
Buy box and criteria. One page of rules that says which deals earn your time: the hours a week you can give the building, the cash you need left after closing, the unit count and submarkets that fit, who pays the utilities, and the return you need for the work. Every listing is checked against it first. If it fails, the answer takes minutes.
-
Searching and underwriting. I ask for the T12, the rent roll, every lease, twelve months of bank deposit statements, the tax bill, the insurance declarations page, utility bills, and service contracts. Rents come from what tenants pay today, not from projected rents. Expenses are repriced as the new owner: taxes as they could change after a sale at your price, a current insurance quote, a professional management fee, and replacement reserves. Then the financing check: the lender sizes your loan from NOI, and a smaller loan than you planned is extra equity you bring.
-
TOPA and rent stabilization, where they apply. In Washington DC, tenants have purchase rights when a covered building is offered for sale, and some units may be under rent stabilization. I line the TOPA timeline up against your financing and underwrite rents at what the law allows. Virginia does not have TOPA. Some Maryland counties have rent control legislation, so the county matters there. An attorney licensed where the building sits confirms the current rules.
-
The offer and the letter of intent. The letter of intent is a short, non-binding outline of the key terms: price, deposit, due diligence length, financing terms, closing date, and the documents you need. A price decides what you pay today. Terms decide who carries the risk for what you have not found yet.
-
Contract terms and contingencies. We keep the inspection, financing, and appraisal contingencies. We size the due diligence period to the building. We read every deadline and what happens if someone misses it, and we write down the date your deposit goes hard. Your document requests go into the contract. Your attorney drafts and reviews the legal documents.
-
Due diligence. Three tracks run at once. Physical: roof, structure, electrical, plumbing, mechanicals, and the units, with repair estimates and your own inspector. Financial: the T12, the rent roll, bank deposits, and tenant estoppels cross-checked, with expenses rebuilt at your costs. Legal: title, the Certificate of Occupancy, zoning, service contracts, leases, and in DC, TOPA and rent stabilization. Every deadline goes on one page with an owner. We write the walk-away list before you are attached to the deal, and every request to the seller goes in writing, priced off an estimate.
-
Coordinating the team. Your lender, inspector, attorney, and title company each own a part. I keep them to one calendar and make sure the title search is ordered early, because title problems take time to clear.
-
Closing. The rate lock, the financing and appraisal deadlines, and the closing date stay on the one-page calendar, each with an owner, until the deal closes.
-
After closing: the 90-day plan. The written plan for you as the new owner, drafted before you close and handed over after. Days 1 to 30 take control: utilities, insurance, security deposits, rent collection, and a letter to every tenant. Days 31 to 60 reset the costs: re-bid contracts, walk every unit, fund the reserve. Days 61 to 90 measure actual income and expenses against your stress test.
I also look at how you would sell before you buy. If you plan to trade up or consolidate later through a 1031 exchange, a qualified intermediary and your CPA run it. My part is the real estate.
Who does what
I represent you as the buyer and coordinate the other professionals. I am a real estate advisor and broker. I am not a tax advisor, an attorney, or a securities representative, and this page is not tax, legal, lending, or investment advice. Your attorney drafts and reviews the legal documents. Your CPA covers tax. Your lender sets the loan terms.
The multifamily brokerage page explains how I represent buyers.
Start with the free Deal Stress Test
The Deal Stress Test gives you a 10-minute screen for an offering memorandum, a 6-step test, a records-request message, a worksheet, and a calculator that shows your stressed NOI, stressed value, estimated maximum loan, and estimated cash needed. It is free, and the calculator runs in your browser.
Bring your offering memorandum
Book a Buyer Consultation and bring the offering memorandum. We stress test it together. The first call is free. Any engagement after it is scoped and quoted in writing before work starts.
Book a free Buyer Consultation and pick a time on the next screen.
Mobile 202-290-1055. Office 202-800-3200. Email shirani@enterprisere.com.
This page is educational only. Rules differ by city, county, and state. Consult a licensed professional where the property is located before you make a purchase decision.
Common questions
Do you represent buyers as well as sellers?
Yes. I take buyer and seller clients on apartment buildings of 4 to 50 units. I hold a real estate broker license in Washington DC, Virginia, and Maryland. Rules differ by city, county, and state, so I tell you up front where a deal sits and who else needs to be on your team.
How far does the work go?
It runs from your buy box through due diligence and closing, and it ends with the written 90-day plan for you as the new owner. I represent you as the buyer and coordinate your lender, inspector, attorney, and title company so every deadline has an owner.
What is a stress test of a deal?
It is the offering memorandum rebuilt the way you would run the building. Rents come from the current rent roll, vacancy is at least 5 percent, and expenses carry a management fee, a current insurance quote, and reserves. The result is a stressed NOI, a stressed value, the loan that NOI is likely to support, and the cash you would bring to closing.
Why does the lender matter as much as the price?
A lender sizes your loan from NOI, then caps it at a share of the price or the appraised value, whichever is lower. If the loan comes in smaller than you planned, you bring the difference as equity. I run the financing check before you write an offer, and I ask your lender for the real rate, amortization, and coverage requirement.
Does TOPA affect me as a buyer?
In Washington DC, yes. TOPA gives tenants rights when a covered building is offered for sale, and some units may sit under rent stabilization. Virginia does not have TOPA. Some Maryland counties have rent control legislation, so the county matters there. Have an attorney licensed where the building sits confirm the current rules before you rely on them.
What happens if the numbers do not work?
I tell you. The result is one of three reads. Go, if your stressed value is at or above the asking price and the cash fits. Counter, if your stressed value is below the asking price, with the worksheet behind your number. Walk, if the price only works at the seller's numbers.
Can I use the free Deal Stress Test without hiring you?
Yes. The Deal Stress Test and its calculator are free and need no commitment. Download the checklist, run the 10-minute screen on your offering memorandum, and decide from there.
Do you give tax or securities advice on a 1031 exchange?
No. I am a real estate advisor and broker, not a tax advisor, an attorney, or a securities representative. If a 1031 exchange is part of your plan, a qualified intermediary runs the exchange and your CPA runs the tax. I work the real estate side and the timeline.