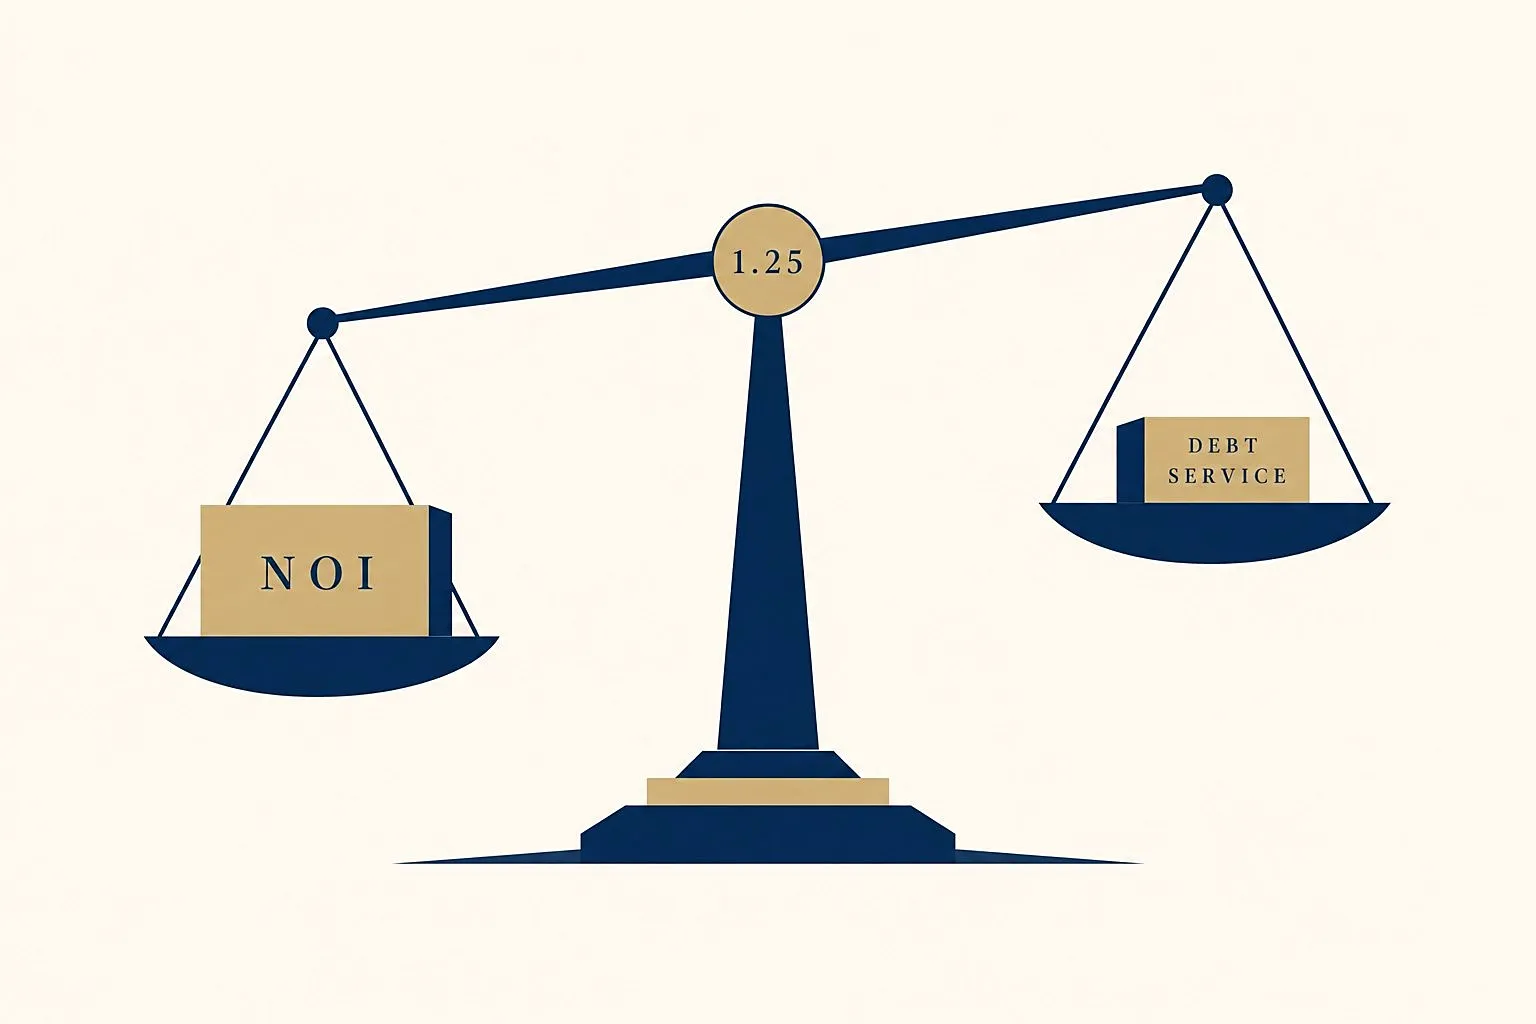
One number decides how much you get, and it does it before anyone looks at your building. If you are heading into a refinance and cannot state your DSCR right now, that is the gap to close first.
DSCR stands for debt service coverage ratio. Strip the jargon and it asks one question. If I hand you this loan, can the building comfortably make the payments?
Take net operating income and divide it by annual mortgage payments. That is the whole calculation.
The formula, with dollars attached
Use the 12-unit building from How to Refinance a Small Apartment Building. The lender says the building produces $275,200 of net operating income. The mortgage costs $220,160 a year.
$275,200 divided by $220,160 gives 1.25.
For every dollar going out to the bank, $1.25 is coming in. Most lenders want 1.25 as a floor.
Below that floor, they do not renegotiate with you. They shrink the loan until the coverage works. That is not a conversation. It is a formula, and arguing with it is the least productive hour of your refinance.
Two tests, and the lower one wins
Owners assume the loan is sized off the building’s value, at around 75 percent of what it appraises for. Sometimes that is the binding constraint. More often the coverage test binds first, and it binds tighter.
On the example building, the value test allowed $3.18 million. The coverage test allowed $2.72 million.
The lender takes the lower number, every time. The loan came in at $2.72 million and the appraisal never entered the decision.
Your loan is not a function of what your building is worth. It is a function of what your building earns in the lender’s version of the numbers, divided by 1.25.
So if you want a bigger loan, there is exactly one input that moves. It is not the appraisal. It is the income the lender uses.
The multiplier: $1,000 of income, $10,000 of loan
At a 1.25 coverage floor and a 25-year amortization, every $1,000 of net operating income you can defend is worth roughly $10,000 of borrowing capacity.
That multiplier runs in both directions, which is the part that costs owners money.
On the example building, the underwriter removed $38,400 of income: $9,600 from moving vacancy off your 3 percent to their 5 percent, and $28,800 from a management fee at 6 percent of $480,000 in gross rents. Run the multiplier across it and the arithmetic is visible: $38,400 times ten is $384,000 of loan proceeds that never showed up.
No repair, no vacancy, no bad tenant. Two assumptions on a spreadsheet.
Run your own DSCR this week
Four steps, and you can finish them in an afternoon with your trailing twelve in front of you.
- Rebuild your income the way a lender will. Start with gross scheduled rent at full occupancy, subtract a 5 percent vacancy factor, normalize expenses to what a building of that age and size should cost to run, add a management fee at roughly 6 percent of gross rents, and subtract replacement reserves.
- Write down your current annual mortgage payment, principal and interest, for the full twelve months.
- Divide the first number by the second. That is your DSCR under lender assumptions.
- Compare it to 1.25 and measure the distance. If you are at 1.40, you have room. If you are at 1.15, you already know your loan is coming in smaller than your model says.
The number that comes out of step three is the honest one. The number on your own income statement is not the one being underwritten.
If step one is the hard part, NOI Leak Check walks the income lines an underwriter adjusts most often.
Do this eighteen months before maturity rather than sixty days before it. A DSCR of 1.15 found early is a problem with four quarters of runway. The same 1.15 found late is a smaller loan.
Own a building in Washington DC, Virginia, or Maryland? Coverage requirements and the income assumptions behind them carry local specifics here: Refinancing a DC Apartment Building
Get a read on your building. Request a building audit and I will calculate your DSCR under lender assumptions and show you which income lines move it.
Frequently asked questions
What is a good DSCR for an apartment loan? Most lenders treat 1.25 as the floor, meaning $1.25 of net operating income for every dollar of annual mortgage payment. Above it you have room to negotiate terms. Below it the lender shrinks the loan until the coverage works rather than reopening the ratio.
How do I calculate my own DSCR? Divide net operating income by annual mortgage payments. Use the lender’s income rather than yours: full-occupancy rent minus a 5 percent vacancy factor, normalized expenses, a management fee at 6 percent of gross rents, and replacement reserves.
Why is my loan smaller than 75 percent of the appraised value? Because the coverage test bound first. Lenders size a loan two ways and take the lower. On the 12-unit example the value test allowed $3.18 million and the coverage test allowed $2.72 million, so the appraisal never controlled the outcome.